ServicesTerm Life Insurance
Term Life Insurance in Terry
A term policy protects your family through the stretch when losing you would hurt most: kids still growing, a mortgage still open and your income paying the bills. We help you choose the length and the amount, then go over every line with you before you sign.
Simple Coverage for a Defined Stretch of Time
A term policy pays your beneficiary if you pass away during the period you select, commonly 10, 20 or 30 years. It builds no cash value, so there is nothing to manage, and the premium is typically a fraction of what whole life would charge for an equal benefit. For many families it is the most straightforward way to replace an income for exactly as long as that income is needed.
The care goes into sizing it. Too little coverage leaves a gap. Too much means paying for protection you will never use. We look at what you owe, what you earn and when each obligation ends, then match a term to those dates. Our agent holds a Life & Health Insurance license and has been in the insurance industry since 2016, so the conversation stays plain and grounded.
What You Get When You Work With Us
- A plan built around your numbers
- We build a personalized plan specific to your needs and budget. The coverage amount and term length come from your real debts, income and family timeline, not a round figure chosen for convenience.
- Options explained without jargon
- We set each option next to the others and explain it in everyday language. There is no pressure, and you decide on your own timeline.
- A one-page coverage summary
- After your policy takes effect, we give you one sheet that lists the coverage you hold, its cost and who it protects. Keep it with your important papers so your family knows where to find it.
- An annual check-in on your beneficiaries
- Once a year we sit down with you to look over your coverage, and we are the ones who put that meeting on the calendar. Part of it is confirming each beneficiary still fits your wishes, because an old name left on a policy can cause real trouble later.
- Help when your family files a claim
- Your family will never have to file a claim alone. We walk them through it personally: which documents the carrier will ask for, how those papers reach the carrier and what the review period looks like. They can reach us by phone at any step along the way.
Signs Term Life Is the Right Fit
Someone depends on your paycheck
If a spouse or children would struggle with monthly bills without your income, term coverage can replace that income for the years it matters.
You carry a mortgage or large debts
A term that lasts as long as your loan helps keep the balance from falling on the people you leave behind. Our Mortgage Protection page covers that option in more detail.
Your children are still young
Many parents pick a term that runs until the youngest child is grown or through college, when the need to replace income naturally eases.
Your coverage through work is not enough
Employer group life tends to pay only one or two years of salary, and it typically disappears the day you change jobs. A personal term policy stays with you wherever you work.
Your life just changed
A new baby, a new job or a new home often changes what your family needs. Let us know about the change, and your coverage is brought up to date no more than a week after you reach us.
What Shapes the Price of a Term Policy
A term premium reflects how likely the carrier thinks a claim is during the years you pick. A handful of factors do most of the work, and we show you how each one moves your quote before you agree to anything.
Your age when you apply
Most level term policies hold the premium steady for the full term. Applying younger usually means that fixed rate starts lower and stays lower for every year after.
Health and tobacco use
Carriers weigh medical history, current conditions and nicotine use. Two carriers can read the same health history quite differently, which is one reason we compare more than one option.
Coverage amount
A larger death benefit carries a higher premium. Bigger policies are often priced more efficiently, though, so doubling the benefit rarely doubles what you pay.
Length of the term
Longer terms carry a higher monthly premium. A policy that runs three decades keeps you covered into older ages, when the carrier expects more claims, while a shorter term ends before then.
Riders you add
Optional features such as a conversion privilege or a child rider raise the premium. We explain which ones make sense for you and which you can leave off.
How Getting Term Life With Us Works
- 1
A conversation by phone
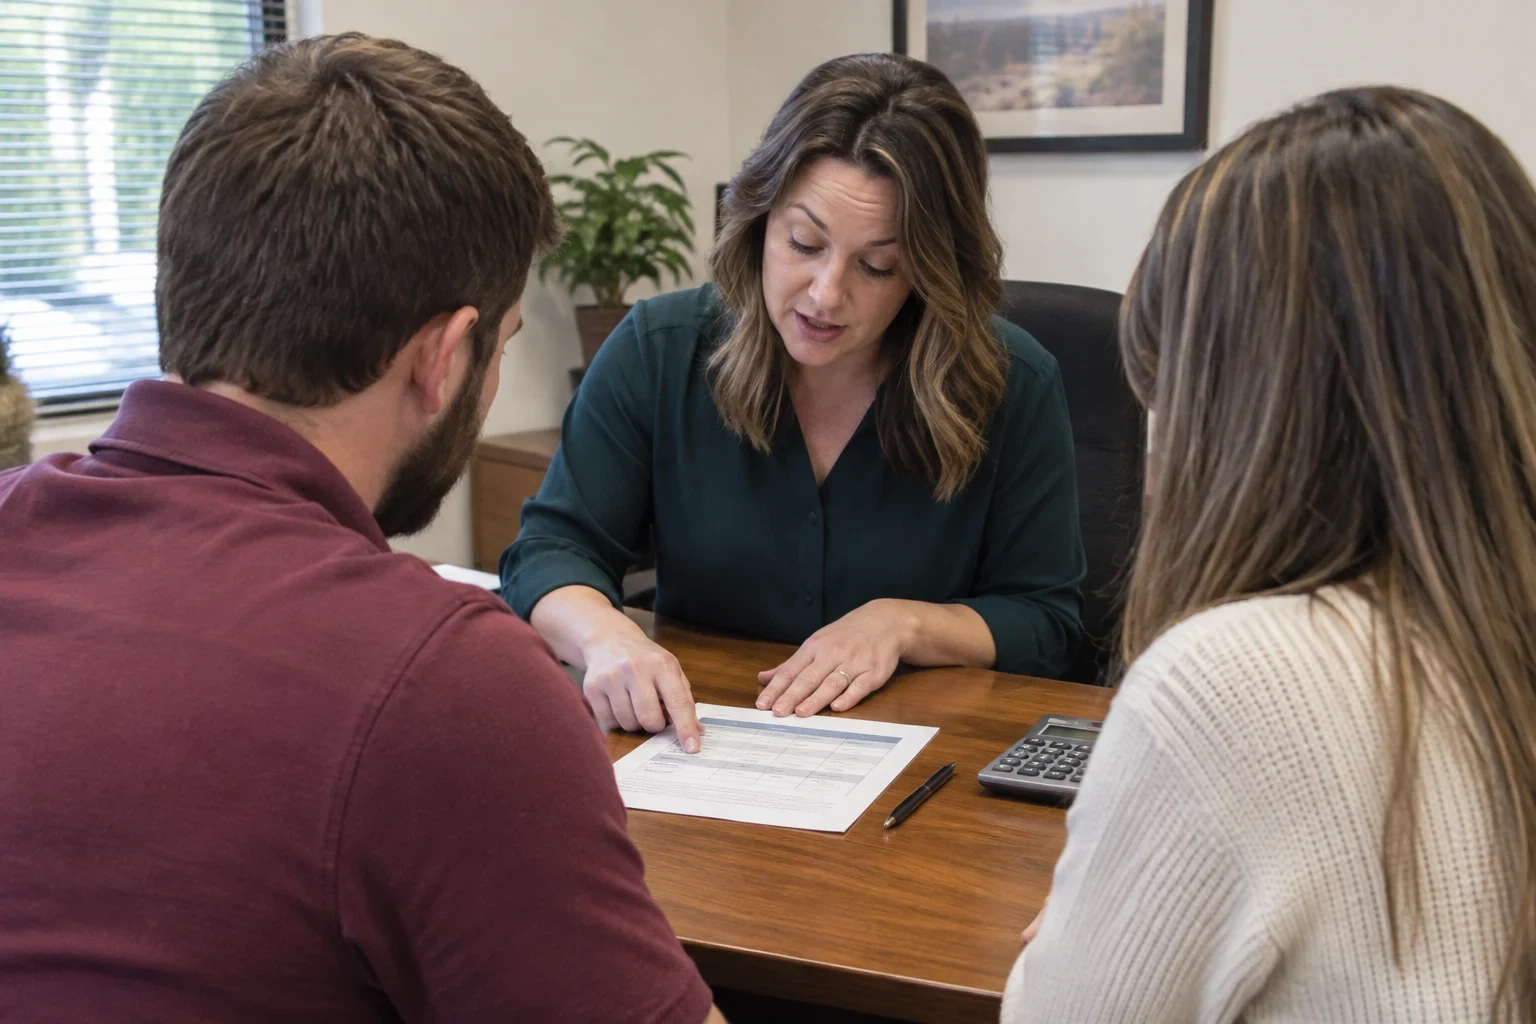
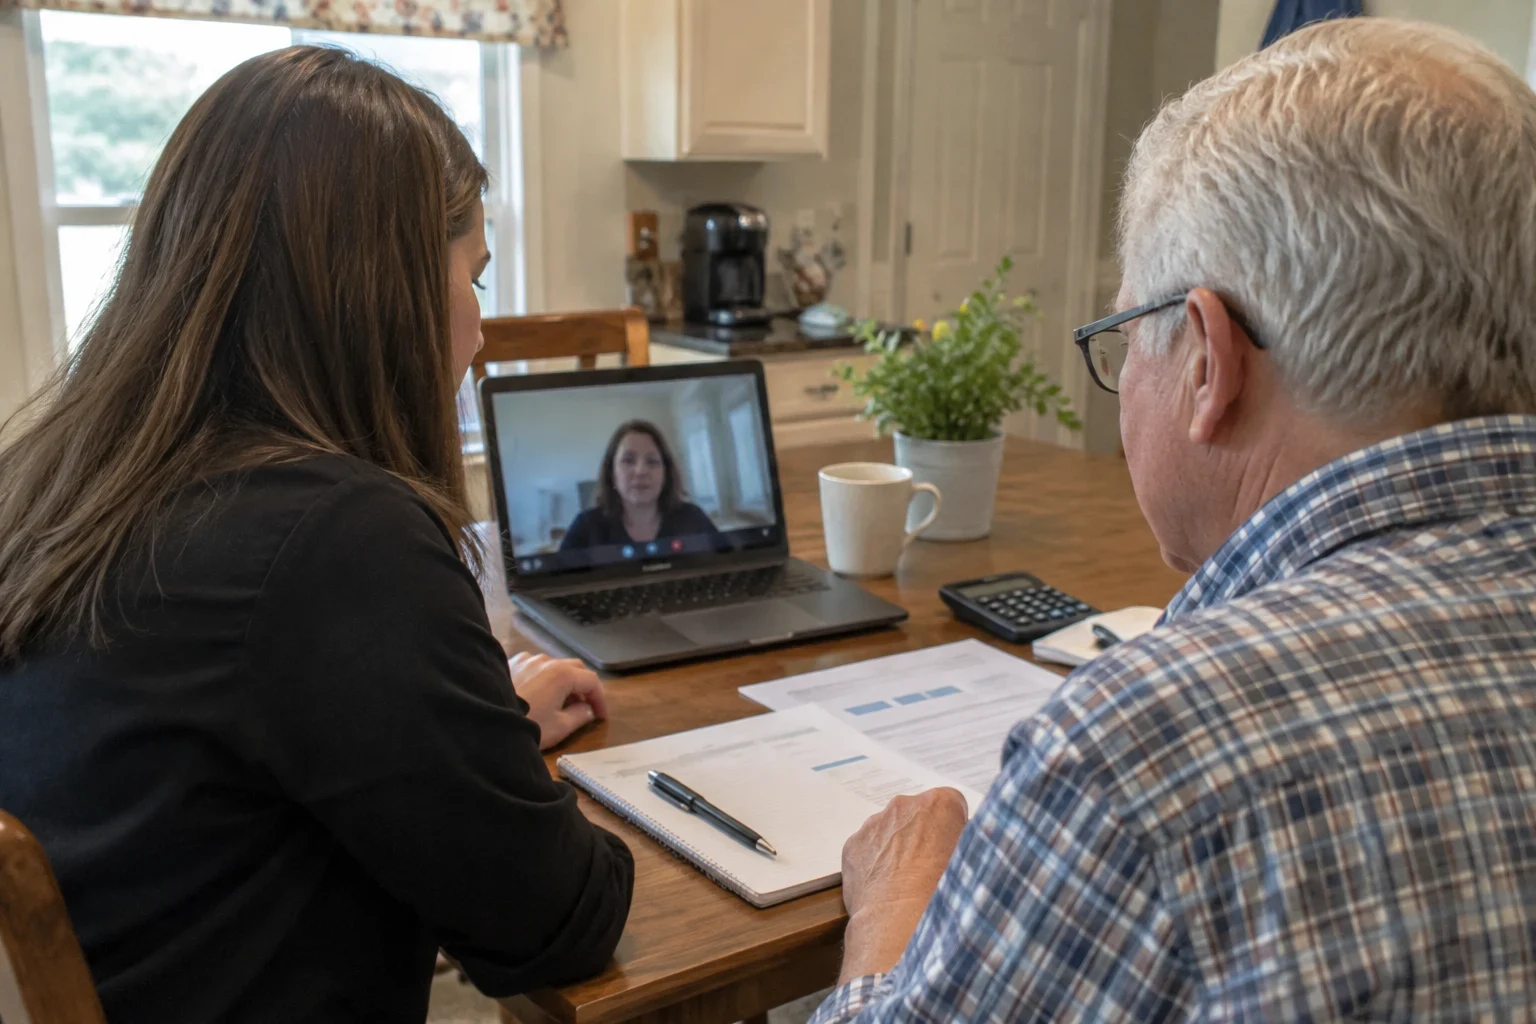
You call and talk to a live person. We ask a few questions about your family and goals and set up a virtual or in-office appointment.
- 2
Sizing the coverage together
At the appointment we walk through your income, debts and timeline. You see quotes for different amounts and term lengths so the tradeoffs are clear.
- 3
Application and underwriting
We help you complete the application. Depending on the carrier and the amount, underwriting may include health questions, a short medical exam or a records check, and we tell you which to expect up front.
- 4
Policy delivery and your summary
When the policy is approved, we go over it with you, confirm your beneficiaries and hand you your one-page summary. Your first yearly review goes on our calendar.
Term Life Questions We Hear Often
What happens when my term ends?
The coverage stops, and no benefit is paid if you are still living. Many policies allow year-by-year renewal at a higher rate. By that point most families have paid down debts and built savings, so the need tends to be smaller. We go over your choices well ahead of the end date at your yearly check-in.
Can I turn term life into whole life later?
Often, yes. Many term policies include a conversion privilege, which lets you switch to a permanent policy without answering health questions or taking an exam again, provided you act before a deadline the carrier sets. The rules vary from carrier to carrier, so we show you exactly what yours allows. Our Whole Life Insurance page explains how permanent coverage works.
Will I have to take a medical exam?
It depends on the carrier and the amount. Some applicants are approved from their health answers and records with no exam at all, while higher coverage amounts often call for a brief one. We let you know which route your application will probably follow before you apply.
How much coverage should I buy?
A sensible starting point covers your debts, several years of income and future costs like your children's education. We build the figure from your own numbers so it fits your budget and what your family would actually need.
Who helps my family if they need to file a claim?
We do. We walk your family through the claim personally, from gathering the death certificate and policy details to keeping in touch with the carrier. We cannot shorten the carrier's review, but your family will not be working through it alone.
Find the Right Term for Your Family
Meet with us by video or at our office in Terry, look at real numbers and take whatever time you need to decide. Families from Byram to Crystal Springs work with us the same way.