ServicesUniversal Life Insurance
Universal Life Insurance in Terry, MS
Universal life is permanent coverage that bends a little. You can raise or lower what you pay, within limits, and adjust the amount your family receives. We walk you through how it works, where it can go wrong, and whether it fits you.
Lifelong coverage with room to adjust
A universal life policy has two parts working together. One is the coverage itself, the amount paid to your beneficiaries. The other is a cash value account. Your premiums go in, the insurer takes out the monthly cost of insurance and fees, and whatever remains earns credited interest.
That structure is what gives you flexibility. In a lean year you may be able to pay less, letting the cash value cover the charges. In a good year you can pay more and build a cushion. The tradeoff is that the policy needs watching, because the cost of insurance rises as you age, and an underfunded policy can lapse.
We hold a Life & Health Insurance license and have been in the insurance industry since 2016. We would rather spend an extra half hour explaining the moving parts than sell you a policy you do not understand.
What working with us includes
- The illustration, read with you
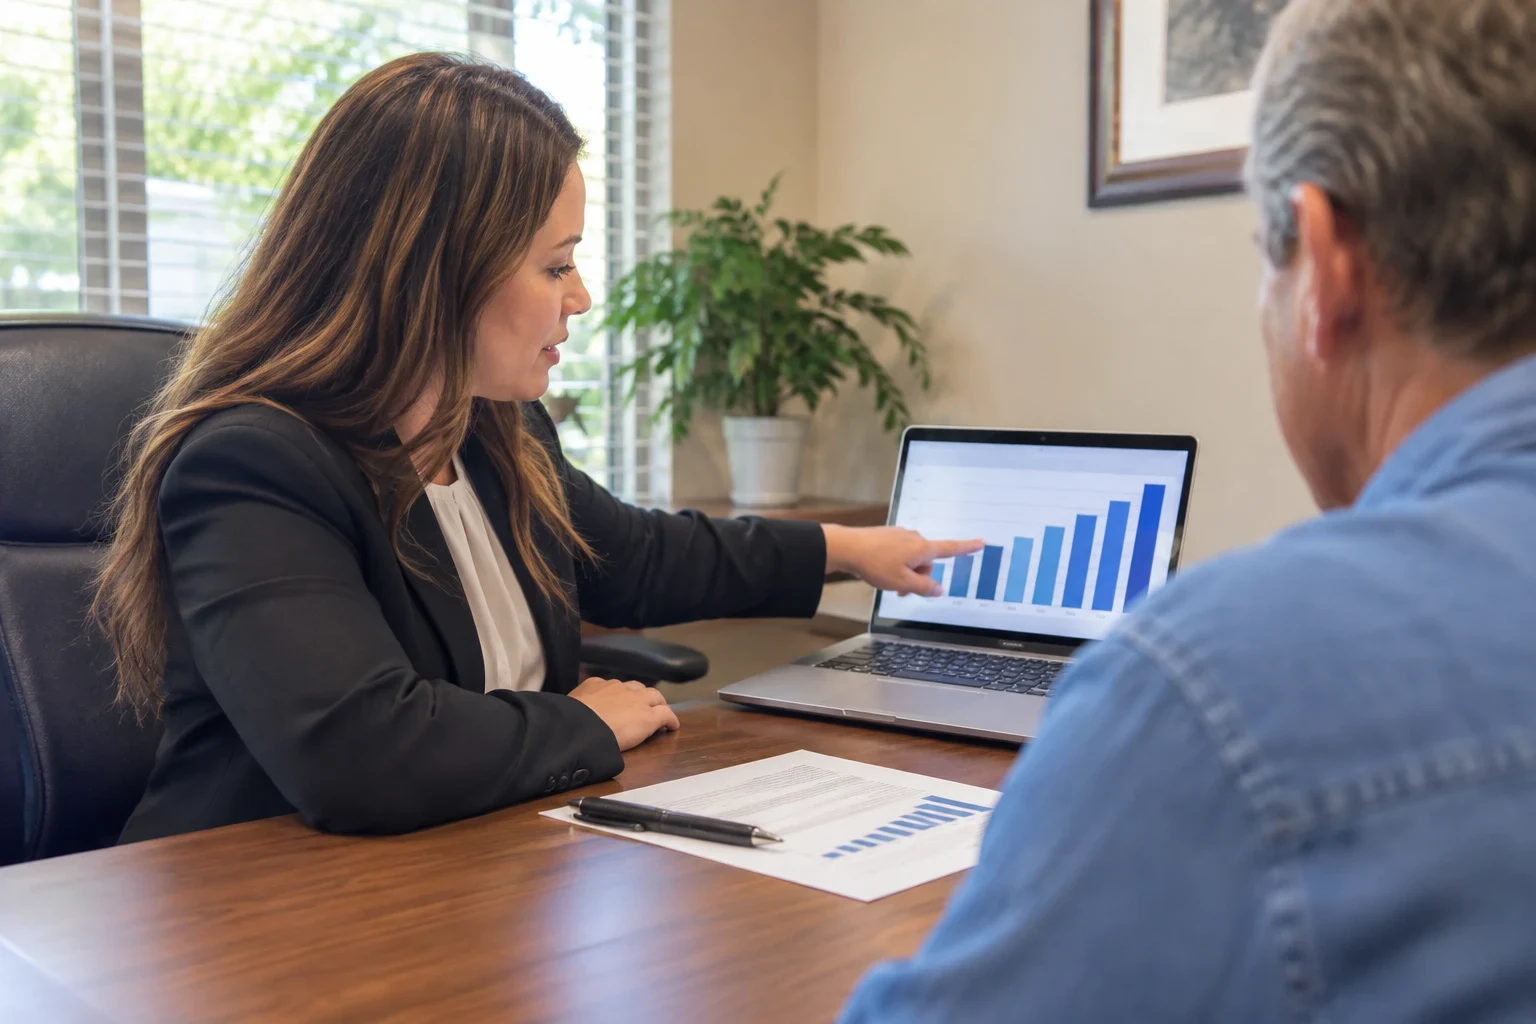
- Every universal life quote arrives with an illustration of projected values. We sit with you and go through it page by page, marking which figures are guaranteed and which are only estimates.
- A plan sized to your budget
- Your plan is built around your own needs and what you can comfortably pay. We aim for a premium that keeps the policy healthy over time, not just the smallest number on the first page.
- No-lapse options, explained
- Some policies offer a no-lapse guarantee when you pay a set premium on schedule. We show what that protects and how much flexibility you trade away for it.
- Your coverage on a single page
- Once the policy is issued, we give you one sheet that lists the policy you hold, its cost and who it protects. It is easy for your family to find and understand.
- An annual check-in on our calendar
- We set up a review with every client each year, so you do not have to remember it. For universal life, that is when we confirm your funding is on track and look over your beneficiaries.
When universal life may be the right call
Your income moves around
Self-employed, paid on commission or working seasonally? Adjustable premiums can make permanent coverage easier to hold onto through uneven years.
Your term coverage is running out
Plenty of people find their term life policy nearing its end date while their family still relies on them. Universal life is one way to carry protection forward for the rest of your life.
Someone will depend on you long-term
A child with lifelong needs, or a spouse who would struggle without your support, may call for coverage that does not stop at a set age.
Whole life feels too rigid
Whole life brings fixed premiums and firm guarantees. If you want more say over payments and coverage amounts, universal life is worth comparing alongside it.
What moves the price of a universal life policy
Your premium comes from two places: who you are on the day you apply, and how you decide to fund the policy. That is why two neighbors of the same age can end up with very different numbers. We lay out the choices side by side before you commit to anything.
Your health and your birthday
Insurers set the monthly cost of insurance from your age and medical history at application. Applying earlier, in good health, keeps that charge lower for the life of the policy. Tobacco and some health conditions push it up.
The size of the benefit
The more your beneficiaries would receive, the larger the charges deducted inside the policy each month.
Your funding level
Paying close to the minimum keeps today's bill small but leaves a thin cushion. Putting in more builds cash value that can absorb rising charges in later years.
Guarantees and added riders
A no-lapse guarantee or optional riders add cost. In exchange, they lock in certainty that a basic policy leaves open.
How it works, from first call to policy
- 1
A short first call
A live person answers, asks a few questions about your family and goals, and sets up a free appointment at our office or by video.
- 2
The appointment
We put universal life next to term life and whole life, walk through sample illustrations, and answer every question in plain terms. There is no pressure, and you choose when to decide.
- 3
Application and underwriting
If you decide to move ahead, we go through the insurer's application questions with you, either at your appointment or over the phone. The insurer then looks at your health history and may ask for a brief medical exam. We call you with updates as it progresses.
- 4
Delivery and setup
Once the insurer approves you, we sit down together with the final contract, double-check who is named to receive the benefit, and give you your one-page summary. If something changes later, like a new baby, a home purchase or a different job, call us and we will update your coverage within a week.
Universal life questions we hear often
How is universal life different from whole life?
Whole life locks in one premium for good, and its cash value builds by a fixed formula the insurer promises up front. Universal life lets you change what you pay and how much coverage you carry, and the interest credited to the cash value can move up or down. You gain more control, and the policy asks a little more attention from you in return.
What happens if I pay less one year?
The insurer pulls the monthly charges from your cash value instead. That is fine as long as enough has built up. If the balance gets low, you will need to pay more to keep coverage active, which is one reason we look at funding every year.
Can my policy lapse even if I have paid for years?
It can, if payments fall behind the cost of insurance as it climbs with age. This catches more universal life owners off guard than anything else. Steady funding above the minimum, or a no-lapse guarantee rider, guards against it, and we cover both before you apply.
Can I borrow from the cash value?
Most policies allow loans or partial withdrawals. Anything not paid back lowers what your beneficiaries receive, and large amounts can put the coverage itself at risk. We show you the effect in numbers before you take one.
Who helps my family when it is time to claim?
We do. Your family will not be left to file on their own; we guide them through the claim in person, explain which documents the insurer asks for, and stay in contact until it is settled. We cannot speed up the insurer's review, but we can help make sure nothing is missing.
Does your IAR credential matter for this policy?
Our agent also holds an Investment Adviser Representative (IAR) credential. With universal life, that background helps when we explain how interest is credited and how cash value projections are built.
See how universal life would look for you
We will sit down with you in our office or over video, show you real illustrations, and leave the decision with you. Families from Byram to Crystal Springs work with us the same way.